✕
Create a free account to see live performance
SEC rules require us to show performance inside a logged-in account.
Every strategy runs live. Inside, you see every holding, every trade, and every move to cash.
SEC rules require us to show performance inside a logged-in account.
Every strategy runs live. Inside, you see every holding, every trade, and every move to cash.
You do not need a math degree to understand quantitative trading. You do need to know how it fails. Here is how it works, the main strategy types, and where it goes wrong.
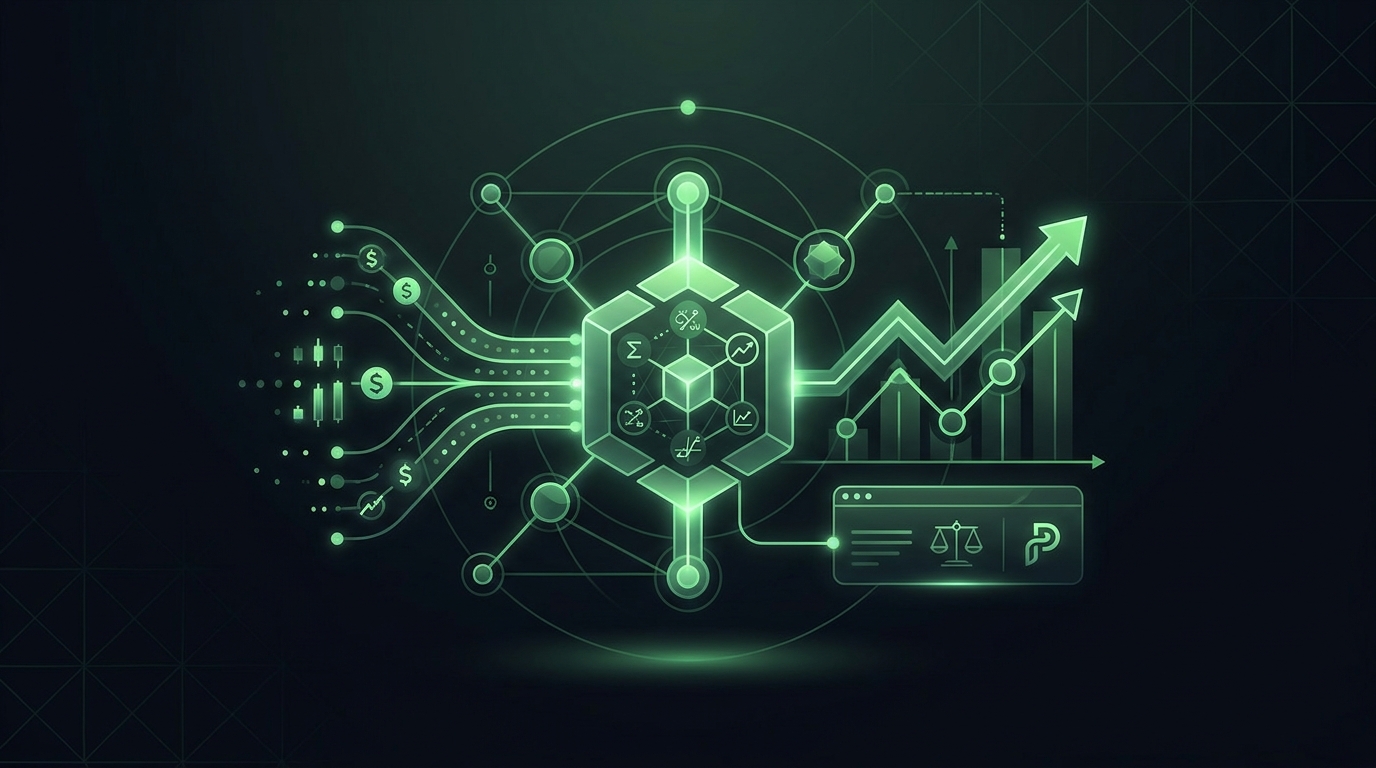
Quantitative trading is a way of deciding trades with data and fixed rules instead of gut feel. You do not need advanced math to understand it. You do need to understand where it fails.
· Quantitative trading, or quant trading, turns an investing idea into rules a computer can test and follow.
· Every quant strategy has 5 parts: data, a signal, a test, risk rules, and execution.
· Common strategy types include momentum, mean reversion, trend following, and factor investing.
· Momentum was documented by Jegadeesh and Titman in 1993, using US stocks.
· The biggest danger is overfitting: rules that match the past but fail on new data.
· Researchers argue most claimed market patterns are likely false, so new ones need strong proof.
Quantitative trading is the use of data and fixed rules to decide what to buy, what to sell, and when. A person writes the rules. A computer tests them on past data, then follows them.
The opposite is discretionary trading, where a person decides each trade by judgment. A discretionary trader might sell because a chart "looks weak." A quant trader sells because a rule says so, every time.
That consistency is the main appeal. The same data always produces the same decision.
Quantitative trading works in 5 steps, from an idea to a live trade. Each step can fail on its own.
Every quant strategy starts with data, such as prices, volume, company earnings, or interest rates. Bad or incomplete data leads to bad rules, no matter how clever the math.
A signal is the rule that says when to act. For example: buy stocks that rose most over the past 12 months. The signal turns an idea into a yes or no.
A backtest runs the signal over past data to see how it would have behaved. Good quants also test on data the rule has never seen, then watch it run live with virtual money.
Risk rules decide how much to put in each trade and when to cut back. They matter as much as the signal. A good signal with no risk rules can still wipe out an account.
Execution is how orders reach the market. Costs and price slippage at this stage can erase a strategy's edge on paper.
Most quant strategies fall into a few families. Each rests on a different idea about how prices move.
Momentum is one of the best-studied ideas. Jegadeesh and Titman (1993) studied US stocks.
Buying past winners and selling past losers earned significant returns over 3 to 12 month holds. Part of those gains reversed in later years.
Quantitative trading most often goes wrong when rules fit the past too closely. This is called overfitting, and it is the biggest risk in the field.
If you test enough rule versions, one will look great by luck alone. The American Mathematical Society shared research showing how fast this happens. With 5 years of data, testing as few as 45 versions can produce one that looks strong on paper but fails on new data.
Rules that keep re-fitting to recent data have the same problem. Read why the best trading models refuse to learn for more.
Researchers have tested hundreds of market patterns. Harvey, Liu, and Zhu (2016) argue that most claimed findings in financial economics are likely false. They say a new factor should clear a much higher bar of proof than usual.
A pattern that works on paper may vanish once trading costs are added. And when many traders follow the same rule, the edge can shrink.
Markets change. A rule built in calm years can behave very differently in a crash. That is why quants watch whether a strategy behaves as designed, not just what it earns.
Yes, regular investors can use quant ideas, and the tools are easier to reach than ever. Charting platforms let you test rules on past prices. Many brokers offer paper trading, so you can watch rules run live with virtual money.
The hard part is not the tools. It is honesty. You need to test on new data, include costs, and accept that most ideas will fail.
AI tools add a new twist. They can write code and explain results, but they do not make a weak rule strong. See do AI trading bots actually work?
Judge a quant strategy by its process and behavior, not by one great return number. Ask these questions.
1. Is the idea simple enough to explain in one sentence?
2. Was it tested on data it never saw while being built?
3. How many versions were tried before this one was picked?
4. Are trading costs and slippage included?
5. Does it behave as expected in live markets with virtual money?
6. Are the rules fixed, or do they keep changing?
Short-term returns are noisy, so luck and skill can look alike. Read judge the behavior, not the returns for a fuller method.
Portfolio Lab is a strategy research and simulation tool from alphaAI Capital. It lets you build investment strategies and test them in live markets with virtual money. It is free to start, with paid plans.
Quantitative trading means using data and fixed rules, tested on past prices, to decide trades instead of gut feel.
Basic math helps, but the core skills are clear thinking and honest testing. Many tools now handle the math for you.
They overlap. Quantitative trading is about deciding trades with data. Algorithmic trading is about placing orders automatically. Many strategies do both.
A backtest runs a set of rules over past prices to see how they would have behaved. It shows the past, not the future.
Overfitting is when rules match past data so closely that they fail on new data. It often comes from testing too many versions.
Momentum trading buys assets that have risen recently, on the idea that strong trends tend to continue for a while.
Some quant strategies have worked for periods of time, and many have not. Research suggests most claimed patterns do not hold up.
AI can help write code and test ideas. It cannot replace sound rules, honest testing, and risk limits.
Build, test, and deploy your own strategies in Portfolio Lab. Free to start.
Educational & Research Disclosure: The content provided is for informational and educational purposes only and is not intended to constitute investment advice, a recommendation, solicitation, or offer to buy or sell any security. Any discussion of market trends, historical performance, academic research, models, examples, or illustrations is presented solely to explain general financial concepts and does not represent a prediction, guarantee, or assurance of future results. Past performance is not indicative of future results. All investing involves risk, including the possible loss of principal.